Luxury is often misunderstood as the accumulation of things, when in truth its deepest form is freedom, the ability to choose, to move, to weather a storm without it dictating your life. Seen that way, the most enviable luxury of all is not an object but a state: financial resilience, the quiet strength that means an unexpected turn of events is an inconvenience rather than a crisis. It is a form of wealth that does not photograph well and rarely gets talked about at dinner, yet it underpins everything else, and at its foundation sits something surprisingly ordinary, namely a healthy relationship with credit. Even for those who feel money is the least of their worries, a strong credit foundation is worth understanding, because it is one of the pillars on which real financial freedom quietly rests.
Why credit matters even when money doesn’t seem to be the problem
It is tempting to assume that credit is a concern only for those who are short of money, but this misreads what a credit profile actually does. Your standing with lenders is not a measure of your wealth; it is a measure of how reliably you handle obligations, and the two are not the same thing at all. Plenty of asset-rich people have surprisingly thin or patchy credit files, because they have never needed to borrow, have let old accounts lapse, or have handled a divorce or a business reversal in a way that left marks behind. When the moment comes to secure favourable terms on a significant purchase, or to move quickly on an opportunity, that overlooked profile suddenly matters a great deal, and a strong one opens doors that a neglected one leaves firmly closed.
The uncomfortable truth is that financial setbacks do not respect wealth. A market downturn, a failed venture, a costly divorce, an illness that upends a household, any of these can leave a mark on the most comfortable of lives, and when they do, a resilient financial foundation is what turns a potential disaster into a manageable episode. In both the United Kingdom and the United States, the same three credit reference agencies, Experian, Equifax and TransUnion, quietly keep the record that lenders consult, and tending that record is part of building a life that can absorb a shock without breaking. Optionality, the freedom to act when you need to, is the real prize, and credit is one of the things that preserves it.
The habits that build a resilient foundation
Building a resilient credit foundation rests on the same unglamorous habits regardless of the size of the balance sheet, which is oddly democratic. The cornerstone is paying every obligation on time, because payment history carries more weight than anything else, and a missed payment counts against a wealthy borrower exactly as it would against anyone else. Beyond that, keeping the proportion of available credit you actually use on the low side signals control, holding long-standing accounts open preserves the length of history that lenders value, and resisting a cluster of applications in a short window avoids the impression of scrambling. Wealth does not exempt anyone from these principles; it simply means the stakes attached to ignoring them can be considerably higher. If anything, a substantial financial life tends to have more moving parts to keep in order, which makes a disciplined, systematic approach to the basics more valuable rather than less, however counterintuitive that may at first seem.
It also pays to keep an eye on the record itself rather than assuming it looks after itself, because errors are common at every income level, and a mistake on your file can quietly cost you the favourable terms your circumstances ought to command. Reviewing your credit report periodically, rather than only when you need to borrow, lets you catch problems early and confirm that the good news is being recorded accurately. For all the sophistication that wealth can buy, this kind of basic vigilance is something no adviser can fully do for you, and the people whose finances are genuinely resilient tend to be those who stay quietly aware of the fundamentals rather than assuming they have risen above them.
Rebuilding when life takes a turn
When a setback does leave its mark, the most important thing to know is that credit damage is rarely permanent, and rebuilding is entirely possible with patience and the right approach. Negative markers fade with time and drop off a file after six years in the United Kingdom and around seven in the United States, and lenders weigh recent behaviour far more heavily than old, so a clean stretch steadily rebuilds a reputation that a difficult chapter dented. The work is much the same as the maintenance: pay on time, keep balances modest, correct any errors, and let the record breathe. Handled steadily, even a serious setback becomes a chapter rather than the whole story.
Sometimes rebuilding involves borrowing again before a file has fully recovered, and there is no shame in that, because used well it accelerates the repair. UK readers working their way back will find that specialist providers of loans for bad credit assess an application around present affordability rather than an ageing score, and readers in the United States will find equivalent lenders in their own market, with every repayment made on time writing a fresh positive line onto the record. The lesson underneath all of it is that true luxury is not immunity from difficulty, which no one can buy, but the resilience to meet difficulty from a position of strength. A well-tended credit foundation is a quiet, unglamorous part of that resilience, and it is available to anyone willing to attend to it, which may make it the most democratic luxury of all.
Author
Written by
Recent Posts
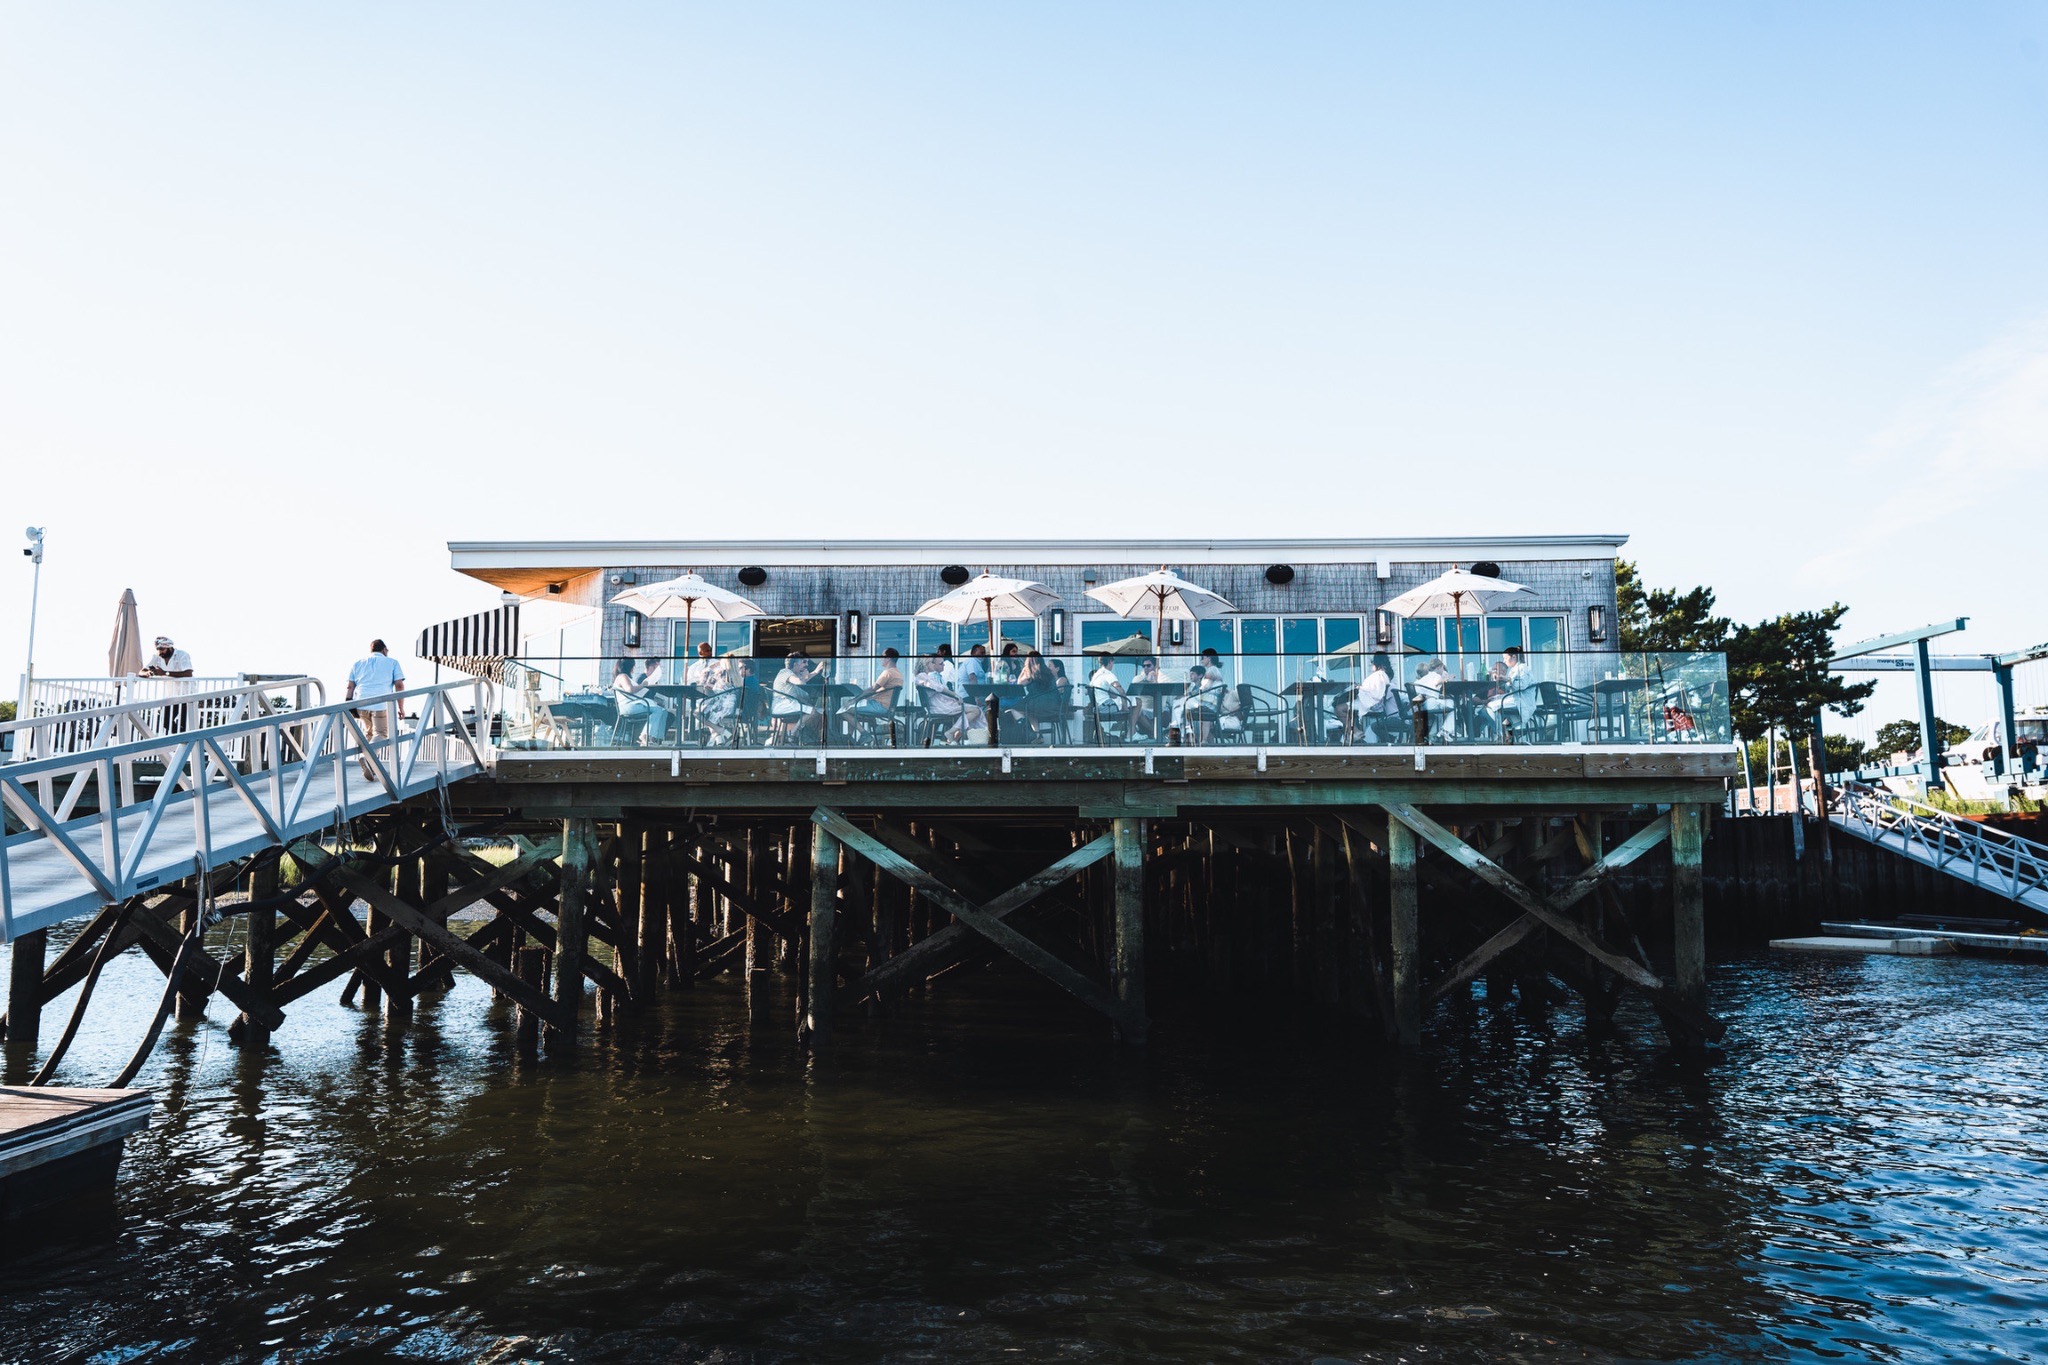
Nino’s Beach Brings Generations of Italian Hospitality to the Port Washington Waterfront
The Self-Made Man Who’s One Phone Call From Ruin
Everyone Out Here Is Loaded. Nobody Feels Rich.
What to Do When Illness Threatens a Trip You Already Paid For
How Independent Watch Brands Are Challenging Traditional Luxury
Categories
- Art
- Articles
- Business of Luxury
- Celebrities
- Culture
- Entertainment
- Events
- Faces of Summer 2026
- Fashion
- Fashion & Style
- Featured
- Finance
- Food, Spirits, Wine
- Hamptons
- Hamptons Celebrities
- Health
- Health & Beauty
- Lifestyle
- Luxury Lifestyle
- Press
- Profiles
- Real Estate
- Technology
- The Chronicles
- Travel
- Uncategorized
- Weddings