Day six of our series on why the rich don’t feel rich. On paper, he is worth tens of millions. At dinner, he still feels a jolt when the check arrives. He is not cheap. He is asset rich and cash poor.
The phrase “asset rich, cash poor” used to describe retired farmers and widows in big old houses. Today, it describes a surprising number of people at the best tables in the Hamptons. They are wealthy on paper and oddly anxious in practice, because almost none of that wealth is money they can actually spend.
The Flinch
Meet Greg. He is a composite, built from a pattern anyone who has dined out on the East End will recognize.
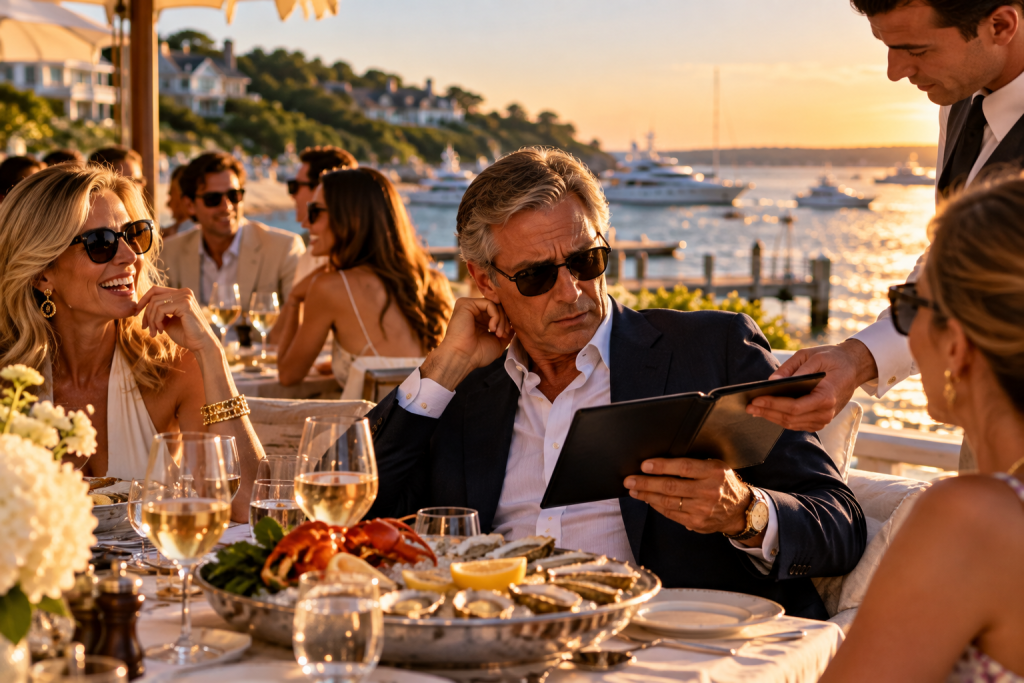
It is a warm Friday at a waterfront restaurant in Sag Harbor. Greg is at a table for eight, celebrating a friend’s birthday. The wine has been excellent and plentiful. The yachts in the harbor are lit up like small cities.
Then the check arrives in its leather folder. Someone jokingly slides it toward Greg, since everyone knows he is the richest person at the table. Greg laughs and picks it up. For a fraction of a second, though, a shadow crosses his face. A small wince. Most of the table misses it. His wife does not.
On paper, Greg is worth something like forty million dollars. So why does a dinner check make him flinch?
Millions on Paper, Not in the Pocket
Here is the answer, and it is less about psychology than arithmetic. Nearly all of Greg’s wealth is locked up.
Most of it sits in shares of the company he helped build. Another large piece is the house in Sag Harbor, plus a share of a commercial building in the city. His checking account, by contrast, holds an ordinary professional’s salary and a modest bonus. In other words, Greg is a multimillionaire with the cash flow of a successful dentist.
He could sell stock, of course. But every share he sells comes with consequences. First, there are taxes. A large sale of appreciated stock can trigger a federal long-term capital gains rate of 20 percent, plus a 3.8 percent surtax on investment income for high earners, plus New York State and possibly city taxes on top. Second, there is conviction. Greg believes the stock will be worth much more in five years, so selling feels like setting money on fire. Third, there is signaling. If he sells, colleagues and investors may wonder what he knows.
So he doesn’t sell. Instead, he lives on his salary, spends like a well-paid professional, and feels every large check in a way his net worth says he shouldn’t.
The Whole Town Is Asset Rich, Cash Poor
Greg is hardly alone. In fact, much of the wealth on the East End looks just like his. It is tied up in homes, private companies, partnership stakes, art, and funds that cannot be withdrawn on a whim. The figures look enormous on a statement. The spendable portion is often surprisingly thin.
This creates a peculiar kind of anxiety, one we touched on in Everyone Out Here Is Loaded. Nobody Feels Rich. Everyone at the party is loaded. Yet many of them are quietly watching their monthly cash flow like a young couple with a mortgage. The difference is that nobody will believe them if they say so out loud.
The flinch, then, is not neurotic. It is rational. Greg’s brain is correctly noticing that this dinner is coming out of the small, liquid part of his wealth, not the big, frozen part. The problem is not that he is cheap. The problem is that his wealth and his life are running on two different clocks.
How Greg Stopped Flinching
The fix for an asset rich, cash poor life is not a mindset. It is a plan. Here is what Greg eventually did, with the help of a good financial advisor and an honest conversation with his wife.
First, they decided what “enough cash” actually meant. They added up what a comfortable year really costs: the house, the kids, travel, generosity, and yes, birthday dinners. That number became their target.
Second, Greg set up a schedule to sell a fixed slice of stock every year, on autopilot. Because the sales are planned in advance, they don’t feel like a bet against the company, and they don’t send a signal to anyone. He pays the tax, and he stops agonizing over the timing.
Third, they created a small cushion, a cash reserve equal to about two years of spending. That cushion is what changed the feeling. Now, a big check does not come from the frozen part of his wealth or from a stressful decision. It comes from a pool of money that exists precisely so he can say yes.
Notably, Greg’s net worth barely changed. What changed was how much of it he could actually feel.
The Check, Revisited
The following summer, the same group went back to the same restaurant in Sag Harbor for another birthday. The yachts were lit up again. The wine was just as good.
When the leather folder arrived, someone slid it toward Greg with the same old joke. This time, Greg simply picked it up, handed over his card, and went back to his story without missing a beat.
His wife watched his face the whole time. No shadow. No wince. Just a man who finally had his money where he could reach it, enjoying a warm night with his friends.
Tomorrow: A Couple Hundred Million Felt Like Real Money, Until He Met the Multi-Billionaires
Author
Written by
Recent Posts
Get Panama Residency in 30 Days — A Simple Look at Mercan’s Easy Program Process
How to Choose a Stay for a Multigenerational Resort Trip
How Family Property Disputes Can Affect Relationships and Long-Term Plans
Choosing a Reformer for the Life You Already Have
Artful Living: Unique Gifts With A Creative Edge
Categories
- Art
- Articles
- Business of Luxury
- Celebrities
- Culture
- Entertainment
- Events
- Faces of Summer 2026
- Fashion
- Fashion & Style
- Featured
- Finance
- Food, Spirits, Wine
- Hamptons
- Hamptons Celebrities
- Health
- Health & Beauty
- Lifestyle
- Luxury Lifestyle
- Press
- Profiles
- Real Estate
- Technology
- The Chronicles
- Travel
- Uncategorized
- Weddings