The National Highway Traffic Safety Administration reported 2.42 million people injured in traffic collisions in 2024. Some of those injuries happen in crashes involving app-based ride-hailing services such as Uber and Lyft. When app-based services take a crash, there’s normally a lot more complexity and claim involvement than there is in a collision between two drivers that don’t work for an app.
Rideshare settlements turn on the same basics as other personal injury settlements. This includes injury severity, medical costs, and fault. They add one more question that can change everything else. Which insurance policy actually applies at the moment of the crash?
What the App Was Doing at the Time
Rideshare coverage usually depends on the driver’s status in the app. A driver with the app off typically has only a personal auto policy. A driver logged in and waiting for a request usually has a middle tier of coverage. Much higher coverage typically becomes available once the driver accepts a ride request.
California’s statutes illustrate how transportation network company insurance limits function. Specifically, in the state, insurance coverage is $50,000 per person, $100,000 per accident, and $30,000 for property damage while the driver is waiting to accept a ride.
Liability coverage is $1 million from the moment a ride is accepted until the ride ends. Coverage for crashes caused by uninsured or underinsured drivers fell to $60,000 per person and $300,000 per incident in 2026 while a passenger is in the vehicle.
The difference between those tiers can decide a claim’s ceiling. A serious injury caused by a driver who had the app off might be covered by a small personal policy, while the same injury during an active trip may be covered by a much larger policy. App data, trip records, and timestamps often become some of the most important evidence in the file.
Putting a Number on the Injury
Once the coverage question is answered, the valuation process resembles that of any other injury claim. The measurable coverage includes medical bills, lost wages, and future treatment. The other part is the non-economic losses, which include physical pain, disrupted sleep, car-related anxiety, and lost family time.
Adjusters and attorneys assign values to these losses. But the calculations can still be disputed in court based on the supporting evidence.
Why These Claims Get Contested
Rideshare claims often involve more parties than a typical crash. The rideshare driver’s personal insurer, the company’s commercial insurer, and sometimes a third driver’s insurer may all have a stake in the outcome. Each of these parties has a reason to argue that another policy should pay.
The presence of conflicting parties can be addressed by being prepared. Having claims clearly showing the entire trip, injuries, and treatments significantly reduces the arguments insurers can present against them, leading to an increased likelihood that insurers will offer higher settlements out of court as a way of preventing expensive losses in court.
Trial experience carries weight in that calculation, and people hurt in rideshare crashes can work with a Costa Mesa rideshare accident attorney when a claim may need to go before a jury.
Fault and Who Was Hurt
Fault still matters, even with larger policies in play. If another motorist caused the crash, that driver’s insurer is usually the first to pay, with rideshare coverage applying depending on the circumstances and the state’s rules. When the rideshare driver caused the crash, the app-based coverage tiers normally apply.
The injured person’s position in the crash also changes the claim. In cases where passengers do not play a role in the accident, their claim may be more straightforward. Cases where the driver has potential fault in the collision can get complicated, even for pedestrians, cyclists, and passengers. Injured passengers can often seek compensation through the rideshare company’s insurance. But the available limits depend on who caused the crash.
Shared fault can reduce a recovery as well. Most states reduce an injured party’s award by their share of fault and bar recovery above a set threshold, usually 50 or 51 percent, while only four states and the District of Columbia bar recovery for any fault at all.
Where Rideshare Coverage Is Heading
State laws governing insurance coverage for ridesharing services are continuing to evolve as legislatures revise the minimal limits for such services. More drivers and delivery services are emerging in conjunction with passengers.
For victims injured in one of these crashes, claim worthiness still depends on how clear the driver’s activity was in the rideshare app as well as the driver’s injuries and the insurance coverage of the other party.
Author
Written by
Recent Posts
What Affects a Rideshare Injury Settlement?
When DUI Charges Get Dismissed
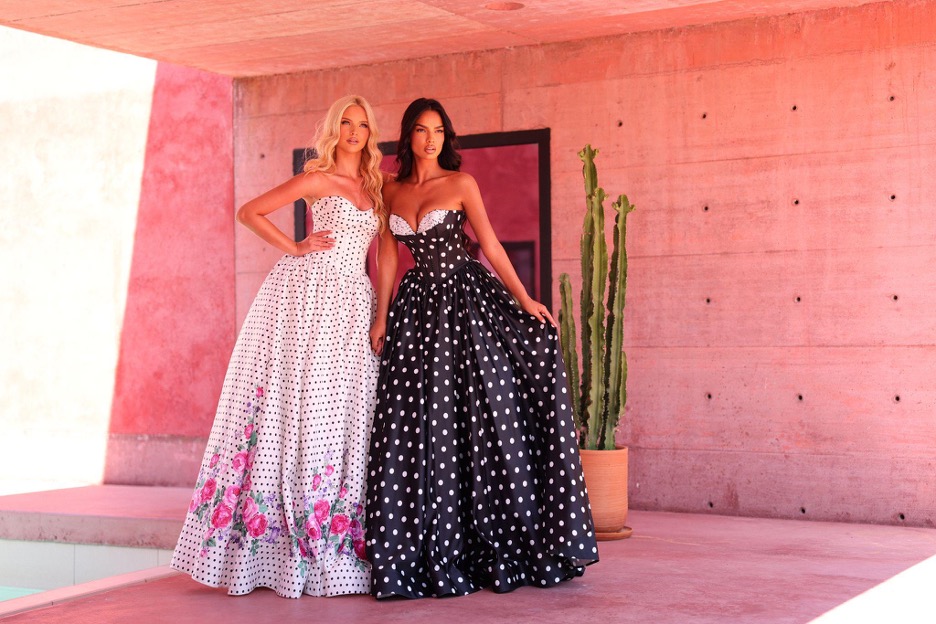
How to Pick a Homecoming Dress for Your Body Type (and Feel Amazing in It)
How to Host a Seasonal Dinner Party Without Overspending
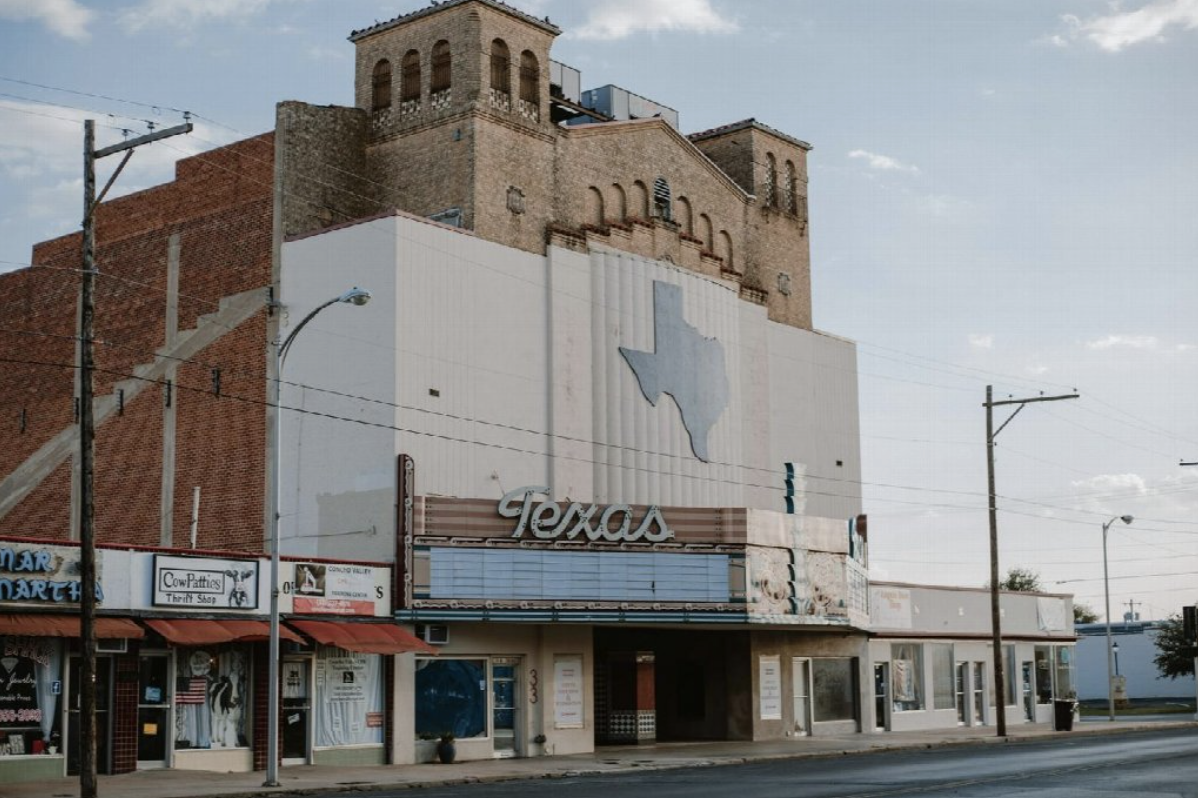
Why Texas Clay Soil Can Be Tough on Your Home’s Foundation
Categories
- Art
- Articles
- Business of Luxury
- Celebrities
- Culture
- Entertainment
- Events
- Faces of Summer 2026
- Fashion
- Fashion & Style
- Featured
- Finance
- Food, Spirits, Wine
- Hamptons
- Hamptons Celebrities
- Health
- Health & Beauty
- Lifestyle
- Luxury Lifestyle
- Press
- Profiles
- Real Estate
- Technology
- The Chronicles
- Travel
- Uncategorized
- Weddings