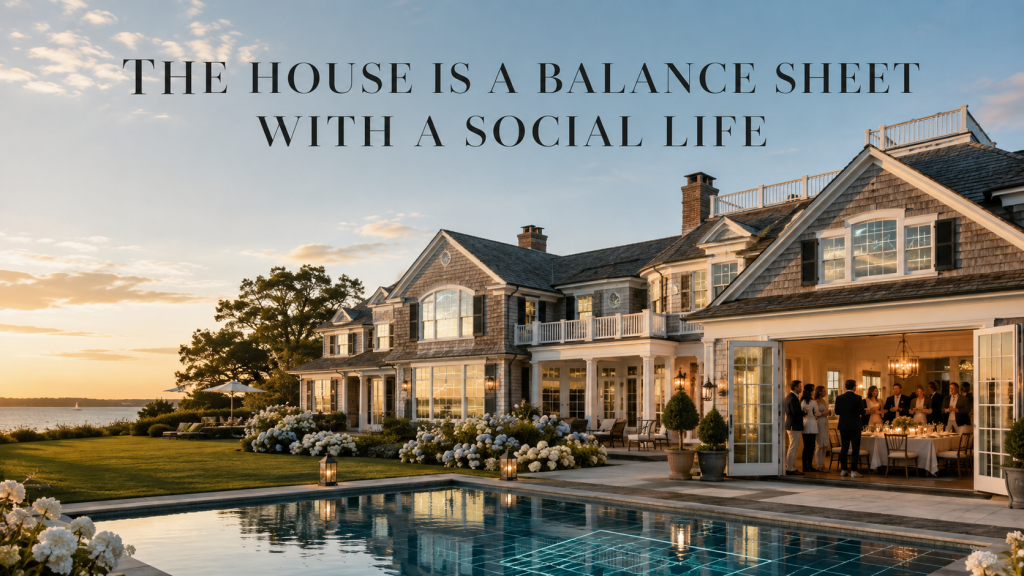
You are standing in the primary bedroom of a house you do not own yet, and the broker is saying the word lifestyle for the fourth time in an hour. You nod at the ocean. But some older part of your brain, the part that got you the money in the first place, is not looking at the ocean at all. It is reading a term sheet. It is right to.
Because a Hamptons house investment is not one decision. It is three positions opened in a single trade. A consumption good you will live in. A financial asset you hope appreciates. And a public disclosure everyone you meet out here will appraise without being asked. No other purchase you will ever make does all three at once. Certainly none does it this visibly.
The Only Asset With a Driveway
Start with what makes the position strange. Your equities are invisible. Your bonds are invisible. Even your plane is invisible most of the year, parked behind a fence at Westhampton. The house is the single line item on your balance sheet that strangers can value from a moving car. They do, constantly, with surprising accuracy.
The disclosure works in both directions, to be fair. A well-chosen house vouches for you in rooms you have not entered yet, a letter of reference written in cedar and privet, renewed every season you keep it.
Financial history treats property as the original store of wealth, the thing worth holding when every paper promise failed. Out here that history is still operating. Land south of the highway is a scarcity trade that has run for a century. Nobody is manufacturing more oceanfront, and the buyer pool keeps minting itself in Manhattan.
Still, the store-of-wealth story is only a third of the position. The other two thirds are the carry and the dividend, and both get systematically misjudged by first-time buyers, usually in opposite directions.
The P&L Nobody Prints
Every house out here runs a profit and loss statement that never sees Excel. On the cost side sits the carry: property taxes, staff, and insurance that reprices upward every renewal now. Add landscaping at a scale closer to agriculture than gardening, the pool, and the pond that turned out to be a wetland with a lawyer. Owners of significant properties routinely carry mid six figures a year before a single guest arrives.
On the income side sit three lines. Appreciation, which is real but lumpy and only collectible at exit. Rental income, if you open the position to the market. That decision has its own status mathematics, and it gets a full article later in this series. And the third line, the one no accountant will book: the standing dividend.
The standing dividend is what the address pays you in recognition, access, and shorthand. It is genuinely valuable and genuinely unpriceable. It is also the reason two houses with identical carry can be wildly different investments. One pays its dividend. The other just costs.
Two cost lines deserve particular respect now. Insurance has become a market of its own, with oceanfront carriers repricing risk every season and some declining to renew at all. Also the labor line, because the trades that maintain these houses book out a year ahead, and the best of them choose clients the way clubs do.
The Hamptons House Investment, Read as a Term Sheet
So read the purchase the way you would read any term sheet, starting with structure. All cash or financed is not a math question out here. It is a personality disclosure, and the county records make it public. Cash says the position is small relative to the balance sheet. Financing says nothing shameful, but it says something. The something is legible to anyone who cares to look.
Next, the collateral clause. A house of this size is a borrowing base, and the sophisticated owners treat it as one. They draw against it when rates make that intelligent. In fact the quietest fortunes out here run the biggest credit lines against the calmest addresses. Borrowing against banked value is cheap. Selling it is loud.
Then the exit provisions. Illiquidity is the real risk in the position, not price. The right buyer for an eight-figure house is a specific person who must exist at the specific moment you need them. In a bad year that person is busy having their own bad year. Price the exit before you sign the entry.
Capex With an Audience
Renovation is where the financial position and the visible position collide, because renovation is capital expenditure that the entire market watches happen. The dumpsters announce the project. The permit filings, public record, announce the budget class. For eighteen months your capital allocation strategy sits on the front lawn.
Sequence matters as much as budget. Owners who renovate in their first year are announcing that the house was wrong, and the announcement outlives the dumpsters. The ones who wait a full cycle of seasons before touching anything are announcing that they bought correctly. Or at least that they can afford to seem to have.
The classic error is over-improvement, and it is a genuine investment error before it is a taste error. Every lane has a ceiling, and capital spent above the ceiling of the lane does not return. The market prices the street first and the marble second. Builders know this. Buyers fresh from a liquidity event frequently do not. They are still pricing effort the way their last industry did.
The opposite play, notably, is the one the oldest positions run: deliberate under-improvement. The unpainted shingles, the kitchen from another administration. That is not neglect. It is an owner declining to perform for the appraisal. That refusal is its own disclosure, and among the most expensive-looking moves available at any price.
What the Purchase Discloses
Understand that the market reads your buy the way analysts read an acquisition. The village you chose sets your comparables. The street inside the village sets your peer group. New construction versus prewar versus farmhouse says how your money relates to time. Hedge height says how it relates to attention.
Equally, the off-market purchase is a disclosure about disclosure. Buying with no listing and no photographs says the buyer values information the way this market values waterfront. It is the most old-money move available inside a transaction, and it costs nothing but patience.
None of this reading is optional, and none of it waits for accuracy. The read happens the week you close, because closings are public record and this market checks. Your only real choice is whether the disclosure is one you drafted or one you defaulted into.
For example, the buyer who chooses the quieter street over the trophy street at the same price has said something specific and flattering about his balance sheet. Whether it is true matters less than you would think. The information war out here is fought in deeds and setbacks. Ammunition is sold by the acre.
Buy, Rent, or Wait
The rent-versus-buy decision runs on different math out here than anywhere else you have run it, because renting is also a position and also disclosed. A rental is the one holding everyone else in the room can price to the dollar. The next article in this series takes that mechanism apart in full.
Buying, by contrast, is the only way to open the standing-dividend line. The dividend accrues to owners on a vesting schedule measured in summers. Yet buying too fast is the most common unforced error in the market. The first season should be a research season. The house you would buy in June and the house you would buy in September are rarely the same house. September’s buyer keeps the difference.
There is a third path the brokers rarely present, although the oldest families use it constantly: the long lease inside the family orbit, the guest house borrowed for a season, the compound quietly absorbing a generation. Housing, for those balance sheets, is an allocation question solved decades ago and merely administered now.
Waiting, meanwhile, costs less than the brokers suggest. The scarcity is real over decades and negotiable over quarters. There is always another house. There is not always another balance sheet as intact as yours is today.
When Selling Says Everything
Every position eventually faces the exit, and out here the exit is the loudest transaction of all. A sale gets read as a symptom until proven otherwise: divorce, margin, succession, or the quiet reallocation of a fortune changing type. Proceeds are private. The signal is not.
The oldest owners solve this by simply never selling, which is why the best streets turn over at the pace of estates being settled. Their houses have stopped being positions at all and become something closer to charter documents. That patience is not available to you yet. But it is purchasable, in installments, and the installments are called summers.
Timing softens the read. A sale in February is inventory. A sale in July is a story. So the owners who must sell in season list quietly and price for speed, because every week on market out here is a week of narrative.
Estates are the exception that proves all of it. A sale from an estate carries no symptom, only calendar, which is why executors get the cleanest prices on any street.
Because of that, the smartest exits out here are partial: the back lot spun off, the barn parcel sold to the neighbor who has wanted it for a decade. Partial exits harvest capital without filing the symptom paperwork. The neighbors read a favor instead of a diagnosis.
What the Homes Business Gets Wrong
The real estate industry out here sells the position almost entirely on the consumption good and the ocean, which is why so much marketing money underperforms. The buyer at this level is not shopping for lifestyle. He is running a term sheet with a view, and he responds to material that respects the term sheet.
The brokers and builders who dominate this market figured that out years ago. They talk carry honestly, price the lane’s ceiling before the client tests it, and treat the standing dividend as the asset it is. Specifically, they sell the position, not the sunset, and their clients repay them with the only currency that compounds in this business: the next three referrals.
The ones still selling sunsets are welcome to keep doing it. Their listings photograph beautifully and sit long.
The Walkthrough, Again
So you are back in that primary bedroom, and the broker is winding up for the fifth lifestyle. Now you know what you are actually holding. A consumption good you will love. An appreciating asset you cannot quickly exit. A credit line wearing cedar shingles. And a disclosure document the whole market will read by Friday.
Buy it or do not. Either way, read every clause first, because everyone else out here already reads yours. The ocean, for what it is worth, really is beautiful. It is also the only thing on the property that was never for sale.
Where The Conversation Continues
If you caught yourself pricing your own carry two sections ago, you are the reader this series was built for. The rest of the room is reading your position either way.
Social Life Magazine has covered this market and its owners for over two decades. For editorial inquiries, reach the editorial desk.
For brands and individuals ready to be part of the story, explore a feature in Social Life.
The people in these pages get the invitations first. Sign up for Event Invites and Specials and read the season before it happens.
The positions described here assemble in person every July. Polo Hamptons, Bridgehampton, where the balance sheets meet.
Print still carries a weight the feed cannot. Subscribe to the print edition and hold the season in your hands.
Independent coverage of this world stays independent because readers keep it that way. Support Social Life’s editorial desk.
Author
Written by
Recent Posts
Why the Supplement Market Is Shifting From More Products to Smarter Choices
5 Ways Engraved Custom Trophies Boost Employee Engagement
Creating Beautiful Mix-and-Match Tablescapes for Any Occasion
Is It Cheaper to Drive or Ship Your Car? We Ran the Numbers
Dear Margo: Restaurateur Dean Pashilis’ Tribute to Family, Food and Hospitality
Categories
- Art
- Articles
- Business of Luxury
- Celebrities
- Culture
- Entertainment
- Events
- Faces of Summer 2026
- Fashion
- Fashion & Style
- Featured
- Finance
- Food, Spirits, Wine
- Hamptons
- Hamptons Celebrities
- Health
- Health & Beauty
- Lifestyle
- Luxury Lifestyle
- Press
- Profiles
- Real Estate
- Technology
- The Chronicles
- Travel
- Uncategorized
- Weddings