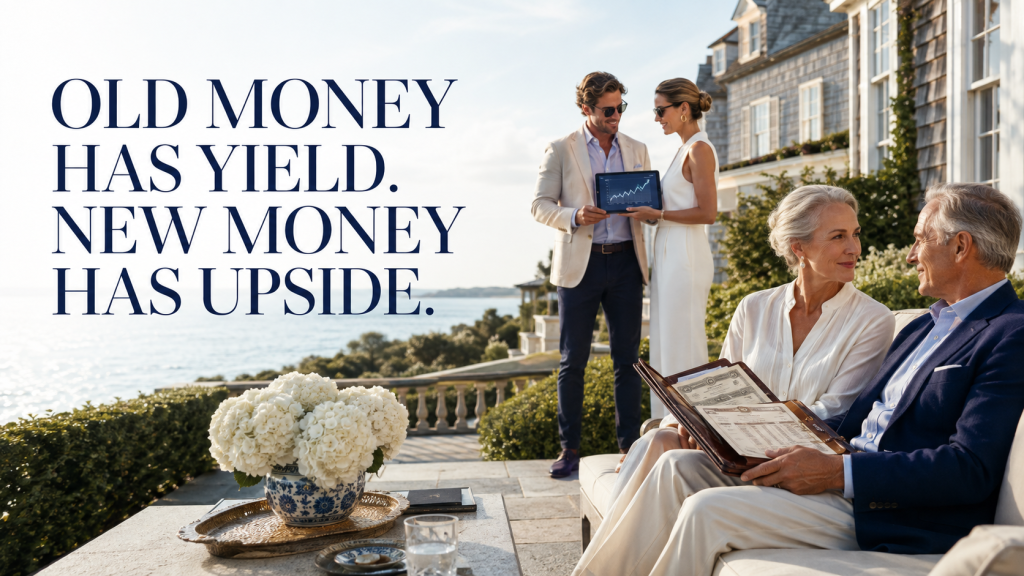
Two men stand at the same rail at a Southampton benefit in late June. Their name tags cost the same. Their net worths, if you could see them, sit within rounding distance of each other. Yet one of them needs this summer to go well, and one of them does not. That difference is visible from across the tent, although nobody at the party could tell you why.
Everyone out here calls it old money new money, and everyone reads it as a birth certificate. Born into it or built it, the story goes, and the room sorts accordingly. But the birth certificate is a symptom. The real document is the balance sheet. One fortune pays its owner quarterly whether he answers email or not. The other lives in a cap table and needs two more good years. Same number. Different animal.
This piece is the first in a series about that difference. Specifically, it argues that the entire social architecture of the East End runs on a single question, and it is not the question anyone asks at dinner.
The Question Nobody Asks Out Loud
The old money new money divide gets written up as taste, as manners, as who wore what to the clambake. Those are downstream. Upstream sits a question so simple it sounds naive: how does the money arrive?
Because money arrives in only a handful of ways. It arrives as yield, the coupon, the distribution, the rent check, income thrown off by assets someone else assembled. Or it arrives as upside, the equity that vests, the company that exits, the carry that clears. In fact those two arrival patterns produce two different nervous systems. Yield relaxes. Upside performs.
Watch it at any dinner between Georgica and Further Lane. The man on yield asks questions and lets silences sit. The man on upside fills silences, because for twenty years silence meant the pitch was dying. Neither behavior is a choice. Each one was installed by an instrument, the way a trade installs a walk.
So the sorting the Hamptons performs every summer is not really old versus new. It is banked time versus borrowed time. That reframe explains almost everything the usual story cannot, including why some first-generation fortunes read as settled within a decade while some inherited ones never stop auditioning. The instrument decides, not the ancestor.
Five Instruments, Five Personalities
Every fortune out here was manufactured by one of five machines: credit, bonds, equity, insurance, or property. The machine leaves fingerprints on the owner long after the money turns liquid, and the fingerprints show up socially before they show up anywhere else.
Credit fortunes are loud because debt is loud. Debt has a clock on it, and people who built with borrowed money never stop hearing the clock, even after the last note is retired. Bond fortunes are quiet because a coupon has no clock, only a calendar. Equity fortunes are anxious until the position clears, and then anxious about the next position, because equity people are trained to believe standing still is dying.
Insurance fortunes, the trusts and the structures and the family offices, are the most patient money in any room. Specifically, they were engineered to outlive their founders, so they behave like institutions instead of people. Property fortunes are the hybrid, part income and part theater. A building is a bond you can throw a party in.
Ask what someone does and you get a rehearsed answer. Ask how the money arrives and you can predict their July, their guest list, their renovation budget, and the volume of their laugh. One of those questions is polite. The other one is useful, and the rest of this series treats it as the only question worth asking.
Yield Is Banked Time
The coupon is the oldest quiet flex in finance. A bond is a promise that the future will pay you for something already done. The Rothschilds understood this before anyone, and their real product was never gold. It was earlier information about which promises would hold, moved across Europe faster than governments could move it.
Yield means the work is finished. The fortune was assembled, seasoned, and converted into instruments that pay without supervision. As a result, the owner of yield has stopped auditioning. He can afford a bad summer, a dull party, a season of saying no. Nothing about his position requires this particular August to succeed, and everyone within thirty feet of him can feel it.
Yield also explains the strange fact that the quietest fortunes out here are often the least examined. Because a coupon never has to introduce itself, nobody asks where it came from, and after enough decades nobody remembers. Forgetting, in this market, is the final dividend.
That is the entire mechanism behind what the room calls old money confidence. It was never breeding. It was duration, dressed as personality. Three generations of coupons will teach any family to stop performing, because performance stopped being load-bearing decades ago. The children are not calmer by nature. They are calmer by portfolio.
Of course the coupon class has its own tell, and it is real estate they refuse to sell. The house that has not traded since Eisenhower is not sentiment. It is a position, held the way their bonds are held, quietly and to maturity.
Upside Is Borrowed Time
Equity runs on the opposite clock. Upside is a claim on a future that has not happened yet, which means its owner is still owed something and still owes something. The position may be worth nine figures on paper. Still, paper is a promise the market can revise by Labor Day, and every holder of concentrated equity knows the revision schedule by heart.
This is why the first summer after an exit always runs slightly hot. The liquidity event converts borrowed time into banked time in a single afternoon, but the nervous system does not convert on the same schedule. The instincts that built the company, urgency, visibility, the reflex to close, arrive in Bridgehampton fully intact. They built the fortune. Then, out here, they discount it.
History keeps teaching this lesson at scale. John Law printed a bubble in 1720 and half of Paris confused paper appreciation with permanence. The pattern repeated in 1929, in 1999, in 2021. Every cycle mints a class of owners who mistake mark-to-market for arrival, and every cycle delivers them to the same hedgerows to learn the difference in person.
The East End does not punish new upside. It simply prices it correctly, and the price includes a waiting period nobody publishes. Later in this series, the summer after the exit gets a full anatomy of its own.
Banked Time Decays Too
Before the coupon class gets too comfortable in this argument, the ledger has a second page. Yield erodes. Fortunes built on nineteenth-century instruments have been quietly shrinking against inflation, taxes, and division by heirs for a century, and the East End records the erosion in deeds.
Look at the estates that have changed hands since the eighties. In most cases the sellers were names, and the buyers were tickers. A family that once summered on forty acres now summers on four, and the difference was purchased by somebody’s carried interest. Duration confers standing, but standing pays no coupon of its own.
This is the quiet half of the old money new money exchange, and it is genuinely an exchange. One side arrives holding money and needing recognition. The other side holds recognition and, more often than anyone admits, needs the money. The benefit committee, the club membership drive, the board seat that comes with a giving expectation, all of it is the market where those two positions trade.
Also worth saying plainly: the erosion is not failure. It is arithmetic. A fortune that stops compounding and starts distributing will eventually be outgrown by one still compounding, and the East End is simply where the crossover becomes visible in acreage. Still, the older fortune keeps one advantage through the whole decline, because recognition, once banked, erodes far more slowly than principal.
Neither side names the trade, of course. Naming it would collapse the price. But both sides clear it, every season, at tables set for twelve.
The House Is Where the Two Meet
Property is the one instrument both sides hold, which is why the house is where the sorting becomes visible. A Hamptons house is the only asset in either portfolio that is simultaneously a position and a stage. The bond stays in the statement. The house gets photographed, toured, borrowed, and judged.
Yield buys a house the way it buys everything, for duration. The shingles stay unpainted because weathering is the return. Upside buys a house the way it built a company, as a project with a completion date, and the completion is the reveal.
Both purchases can run twenty million dollars. Yet the two buildings communicate opposite balance sheets, and everyone invited to either one reads the disclosure without knowing they are reading. A hedgerow is a financial document. So is a gut renovation, and so is the decision not to gut.
Notably, the two buyers even disagree about what the asset is for. On the yield side, the house is infrastructure, a place where the family record accumulates. On the upside side, at least in the first years, the house is evidence, proof that the exit was real. Infrastructure appreciates quietly. Evidence needs an audience, and audiences out here take attendance.
The house question also explains the rental market’s strange status physics, because a rental is the one property position everyone else in the room can price to the dollar. That mechanism deserves its own piece, and it gets one in this series.
What Old Money New Money Actually Measures
Put the instruments away for a moment and the pattern underneath is a single variable. The old money new money divide measures duration, nothing else. How long has the fortune existed in a form that no longer requires its owner to perform?
Compound interest and inherited taste are the same mechanism running on different collateral. Both take principal that someone else assembled. Both throw off returns that feel, to the holder, like natural law. A trust fund and an instinct for which paintings not to buy are equally unearned and equally real. Each one compounds silently, and neither can be acquired in a single transaction.
This is why the divide survives every attempt to buy across it. Money moves at the speed of a wire transfer. Recognition moves at the speed of repeated summers. The gap between those two speeds is the discount every new fortune pays, and no banker can structure around it, because the shortfall is not denominated in dollars.
For example, take two men with identical nine-figure statements, one four summers old and one forty. The room does not consult the statements. It consults the record, because the record answers the only question standing actually asks: has time already voted on this fortune, or is the vote still open?
Duration, in the end, is the only asset class the East End respects without an appraisal. Everything else out here gets marked to market. Time in position never does. So old money new money is less a class system than a credit rating, issued by a room instead of an agency, and reviewed every single season.
The Conversion Path
Fortunes do convert. The route is just longer than anyone liquid wants to hear, and it runs in a fixed order: money, then assets, then access, then taste, then relationships, then recognition. Skipping steps is the most expensive mistake made out here, because each skipped step gets charged back later with interest.
Money into assets is the fast leg. Anyone with a wire and a broker completes it in a season. Assets into access is slower, because access is priced in invitations, and invitations clear on a different exchange with different market makers. Access into taste is slower still. Taste is not knowing what to buy. It is knowing what not to, and negative knowledge only accumulates through witnessed years.
Taste into relationships, relationships into recognition, those legs are measured in summers, sometimes in a generation. The first generation banks the principal. The second acquires the fluency. Eventually the third inherits something the first could never purchase, a family that no longer reads as a transaction.
Of course the path can stall at any leg, and it usually stalls at taste, because taste is the first leg that cannot be delegated. A buyer’s agent can source the assets. A publicist can source some access. But nobody can hold the negative knowledge for you, and the room tests for it constantly, in ways designed to look like small talk.
Nothing on that path is fair. Everything on it is legible, once someone names the sequence, and the rest of this series walks it leg by leg with the instruments in hand.
Why the Discount Exists
A fair question follows: who benefits from making new fortunes wait? Because a waiting period this durable is never an accident. It is a defense, and defenses protect something specific.
Yield’s only vulnerability is supply. If recognition could be bought at market, every liquidity event would mint instant standing, and the value of banked time would collapse overnight. The waiting period is how the coupon class protects its one scarce holding. Not beauty, not houses, not board seats. Time in position, the single thing upside cannot manufacture at any price.
So effort gets read as a tell, and speed gets priced as a discount, and the rules stay unwritten precisely because unwritten rules cannot be studied for. None of this is a conspiracy. It is a market defending its reserve currency, and it behaves like every scarcity market in the financial record, with one difference. This one settles in invitations.
Equally, the discount is not personal, although it always feels personal to the person paying it. A market does not dislike new capital. In fact it depends on new capital, the way the benefit circuit depends on new tables. The discount is simply the spread the incumbents charge for underwriting a fortune that time has not yet rated.
Notably, the defense has a weakness, and the smart new fortune finds it. The system discounts buyers. It has always paid a premium to builders, and the distinction between the two is the most actionable idea in this series.
What the Smart Money Does Instead
The losing strategy announces itself every Memorial Day: outspend the waiting period. Bigger house, louder benefit table, a party staffed like a product launch. Every dollar of it reads as borrowed time trying to pass as banked time, and the room marks it accordingly, usually before the valet line clears.
The winning strategy is older and cheaper. Stop buying proximity and start building position. Host small before hosting large. Fund the institution before joining its gala. Buy the house you intend to die in, then let it weather. Above all, put years on the board in one place, because duration only compounds when it stops moving.
For example, the fortunes that converted fastest in East End history were never the largest. They were the ones that picked a lane, a cause, a village, a table, and repeated it until repetition became record. The record is the asset. Everything else is marketing, and the room can smell the difference blindfolded.
Then there is patience with the calendar itself. The families that converted well treated seasons the way their bonds treated coupons, as scheduled installments rather than campaigns. Show up, host modestly, repeat. After all, a record is nothing but repetition that survived long enough to be noticed.
There is also a shortcut, and it is the only honest one. Standing can be witnessed into existence faster than it can be waited into existence. But witness requires a room, and rooms are the subject of this entire series.
What Kind of Money Is in the Room
Every argument above compresses into a single professional skill: reading a room by instrument instead of by net worth. The advisors who last out here already do it instinctively. They know a client on yield needs preservation and a client on upside needs translation. In addition, they know the second service bills higher, because the stakes are social as well as financial and the client can feel it.
The rest of this series takes the instruments one at a time. First the coupon class, and why it never needs August to go well. Then the summer after the exit, and why it always runs hot. A rental, read properly, is a financial product everyone else in the room can price. Two Scottish ministers accidentally invented your family office, and that story explains more about dynasty than any estate lawyer will. After that, the house as the only asset that is also a stage, and finally the new corridors the next wave of money is already traveling. Also ahead: why Wall Street built this coastline on purpose, the twenty million dollar house nobody important visits, and what financial brands get wrong when they market to all five audiences at once.
Brands face the same reading problem in reverse, because a sponsorship pitched at yield fails on upside, and the reverse. In particular, the financial firms that market well out here segment by instrument before they segment by net worth. The ones that do not keep buying impressions in rooms where nobody was ever going to move.
By the end, the party at the top of this page should read differently. Two men at a rail, one clock ticking, one calendar turning. Now you know which is which.
Where The Conversation Continues
If you recognized yourself at that rail, either man, you already know which conversion leg you are standing on. Most people out here never find out which one the room has assigned them.
Social Life Magazine has covered the people and the rooms that decide these things for over two decades. For editorial inquiries, reach the editorial desk.
For brands and individuals ready to be part of the story, explore a feature in Social Life.
The people in these pages get the invitations first. Sign up for Event Invites and Specials and read the season before it happens.
Some conversions happen faster in person. Polo Hamptons is where the room described in this article actually assembles, every July, in Bridgehampton.
Print still carries a weight the feed cannot. Subscribe to the print edition and hold the season in your hands.
Independent coverage of this world stays independent because readers keep it that way. Support Social Life’s editorial desk.
Author
Written by
Recent Posts
Why the Supplement Market Is Shifting From More Products to Smarter Choices
5 Ways Engraved Custom Trophies Boost Employee Engagement
Creating Beautiful Mix-and-Match Tablescapes for Any Occasion
Is It Cheaper to Drive or Ship Your Car? We Ran the Numbers
Dear Margo: Restaurateur Dean Pashilis’ Tribute to Family, Food and Hospitality
Categories
- Art
- Articles
- Business of Luxury
- Celebrities
- Culture
- Entertainment
- Events
- Faces of Summer 2026
- Fashion
- Fashion & Style
- Featured
- Finance
- Food, Spirits, Wine
- Hamptons
- Hamptons Celebrities
- Health
- Health & Beauty
- Lifestyle
- Luxury Lifestyle
- Press
- Profiles
- Real Estate
- Technology
- The Chronicles
- Travel
- Uncategorized
- Weddings