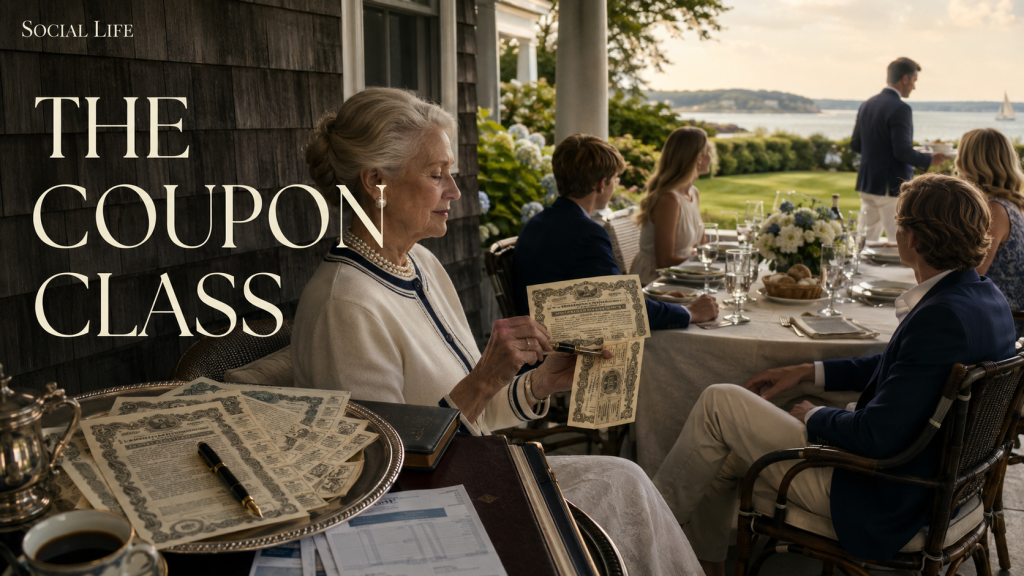
She is at the benefit every June, always at the same table, always slightly to the left of the important people, which is how you know she outranks them. Her money is older than the cause. Her checkbook is older than the honoree. When the auctioneer begs, she examines her bracelet, and the bracelet, of course, has a story she will never tell at this table.
She is inherited wealth, and the phrase gets used out here as if it explained anything. It explains nothing. What she actually inherited was not money. It was machinery, a set of instruments assembled by dead people, still running, still paying, and the machinery is the whole story. This piece is about the machinery.
What Inherited Wealth Actually Inherits
The estate that transfers is mostly paper. Municipal paper, treasury paper, the dividend stack, the partnership interests, the trust that owns the trust that owns the house. All of it engineered to do one thing on schedule: pay, quarterly or semiannually, forever, without requiring anyone alive to be talented.
So the heir inherits income, but also something rarer, the absence of a reflex. She never learned to pitch because nothing in her life ever depended on a pitch landing. She never learned urgency because the calendar handled everything. In fact the famous old money calm that fills a certain kind of room is simply this: three generations of nobody needing anything by Friday.
Also inherited, and underrated: the paperwork habits. The files, the deeds, the letters from lawyers dead fifty years. Inherited wealth keeps records the way other families keep photographs, because the family understood early that the money is the archive. Lose the paper and you are merely rich, briefly.
There is a fourth inheritance, the least discussed: the professionals. The estate lawyer whose father served her father, the bank officer who calls twice a year, the accountant who knows which cousin cannot be trusted with the lake house. Inherited wealth arrives fully staffed, and the staff, in most cases, outperforms the heirs.
The Bond Under the Family
Every coupon fortune stands on the same nineteenth-century invention: the tradable promise. A bond is the future agreeing, in writing, to pay you for something already finished, and the families that mastered that instrument early built positions that are still paying for July out here two centuries later.
Nathan Rothschild remains the patron saint. In 1815 his couriers crossed the Channel with news of Waterloo ahead of the government’s own dispatches, and what he traded on that head start became legend, then myth, then marketing. Notably, the family never much corrected the myth. A reputation for knowing first is itself an asset, and it compounds like one.
The mechanics deserve one plain paragraph, because they explain the timing. A family converts a fortune into promises when the founder stops trusting the future to be as kind as the past. Equity is a bet the family keeps winning. Paper is the decision to stop betting. So the timing of that decision, more than the size of the original pile, separates the families still here from the ones on the historical society’s wall.
The lesson the coupon class took was never the speed. It was the product. Sell certainty, own promises, and let other people own adventures. Adventures, as any trustee will tell you softly over lunch, are what the beneficiaries are for.
When the Paper Fails
The class also inherited its scar tissue, because paper fails, and the failures are instructive. The Confederacy borrowed against cotton it could no longer ship once the Union took the ports, and the bondholders of that lost cause learned what a promise is worth when the thing underneath it dies. European drawing rooms held that worthless paper for decades, framed, occasionally, as a joke with a moral.
The moral survived better than the bonds. Trust no single promise, however patriotic its stationery. Spread the paper across countries, currencies, and courthouses. Above all, distrust anything paying too well, because yield is a price, and a high one is the market telling you something the brochure is not.
Remember this when the calm at that June table reads as innocence. It is the opposite. Inherited wealth is survivorship bias wearing good linen. For every family still cashing coupons, a dozen bought the wrong promise and vanished from the guest lists so completely that nobody remembers to miss them.
Closer to home, the class remembers 1929 the way other families remember weddings, by who behaved well. Trusts written in the twenties saved names that portfolios could not. In fact the drafting habits of that decade, the spendthrift clauses, the skipped generations, still decide which families sit where at dinner a century later.
Why August Never Matters
Here is the social consequence of the machinery, and it is the entire mystique. Nothing in her year is load-bearing. The distributions arrive whether the summer goes well or badly, so no dinner is an audition, no introduction is a pipeline, and no season needs to be a success.
That indifference is unbuyable, which is precisely why the room prices it so high. Everyone else at the benefit needs something from the benefit. She attends the way weather attends. As a result, her yes carries absurd weight and her no costs her nothing, and both facts are known to every chair of every committee between here and Manhattan.
For everyone else at the table, the practical question is what her indifference does to prices. It sets them. An economy of people needing August prices itself against the few who do not, the way every market prices itself against its least motivated seller. She is the risk-free rate, wearing pearls.
Watch what happens when she does want something. The room reorganizes itself with a speed that embarrasses everyone involved, because scarcity works on people exactly the way it works on paper. The rarest bid in the Hamptons is a bid from someone who never bids.
What They Refuse to Sell
The clearest field mark of the coupon class is the refusal. Every one of these families holds something illiquid, underperforming, and utterly untouchable. The land that should be four lots. A house no consultant can justify. The board seat, the pew, the slip at the yacht club held since the club had a waiting list of eight.
An analyst would call these positions sentimental. The family understands them better. They are the collateral under the name, and the name is the instrument that pays best of all. Selling the land converts it to money, and money is the one thing the family already has in the correct amount. The refusal is not stubbornness. It is portfolio theory, applied to standing.
Equally telling is what they sell without ceremony. Stocks go, funds churn, the city apartment trades every decade. Liquidity is for instruments. Permanence is for identity, and the family has never once confused the two accounts.
So when one of these holdings finally trades, pay attention, because it is the loudest sentence the family will ever publish. The paper failed, or the marriage did, or the fourth generation finally outvoted the third. Every deed tells. Theirs tell most.
The Steward and the Spender
Every coupon family runs the same internal casting call each generation, and the family’s future depends on the outcome. One heir gets the machinery and understands the job: keep the instruments running, add nothing reckless, die without headlines. The steward. Everyone else gets distributions and adjectives.
The steward’s life is genuinely strange, and strangely modest. He is rich the way a lighthouse keeper is nautical, professionally, on behalf of something else. His actual employer has been dead since Truman. His performance review is conducted by great-grandchildren who do not exist yet, and he takes it seriously.
Watch for the steward at the June benefit, because he is findable. He is the one who knows the endowment’s actual number, having read the filing, and he asks the treasurer one quiet question that ruins the treasurer’s evening. Stewardship travels. A man who maintains his own family’s machinery cannot resist inspecting everyone else’s.
Families fail when the casting fails. A generation of all spenders and the paper scatters. A generation of all stewards and the family calcifies into its own museum, which is elegant, but museums do not attend benefits. The class survives on the ratio, and everyone inside it can recite which cousins are which.
Buying Into the Coupon Class
Every year some newly liquid fortune notices all this and attempts the obvious trade: buy the same paper, wear the same calm. The paper part works. Municipal bonds are famously available. Yet the calm does not transfer with the CUSIP, because the calm was never in the instrument. It was in the decades of not needing to check.
What actually converts a fortune into this class is the drafting, done early and done boring. The trust established while the money is young, the machinery built before the children can remember its absence. In particular, the families that manage the crossing in two generations instead of four all made the same move: they hired the archive before they needed it.
That is the honest advice hiding in this species profile, and any decent advisor out here gives it. You cannot buy her seat at the table. But you can start the clock on your grandchildren’s, today, with paperwork, and the paperwork is the least glamorous purchase this market sells.
What She Wants From the Room
Nothing is for sale to her, which confuses everyone whose living depends on selling. She has the goods, the houses, the memberships. What the coupon class actually shops for out here is continuity: institutions worth outlasting, causes with longer clocks than donors, and the occasional new person who understands that the correct response to her is neither pitch nor curtsy.
Specifically, she collects competence. The doctor worth keeping, the young trustee who reads the documents, the editor who spells the boat right. Enter her ledger as reliable and you will stay in it for decades, because the coupon class runs its people the way it runs its paper. Long positions. Rarely traded.
The machinery hums along regardless. Coupons pay in January and July. The bracelet keeps its story. She will be at the same table next June, slightly to the left, and the money will be one year older, which is the only performance it ever needed. It works. She does not have to. That was the whole design.
Where The Conversation Continues
If you have ever sat across from that table and wondered what the calm costs, now you know. It cost three generations, and it was paid in advance.
Social Life Magazine has covered these families and their rooms for over two decades. For editorial inquiries, reach the editorial desk.
For brands and individuals ready to be part of the story, explore a feature in Social Life.
The people in these pages get the invitations first. Sign up for Event Invites and Specials and read the season before it happens.
The coupon class and everyone converting toward it assemble every July. Polo Hamptons, Bridgehampton.
Print still carries a weight the feed cannot. Subscribe to the print edition and hold the season in your hands.
Independent coverage of this world stays independent because readers keep it that way. Support Social Life’s editorial desk.
Author
Written by
Recent Posts
Why the Supplement Market Is Shifting From More Products to Smarter Choices
5 Ways Engraved Custom Trophies Boost Employee Engagement
Creating Beautiful Mix-and-Match Tablescapes for Any Occasion
Is It Cheaper to Drive or Ship Your Car? We Ran the Numbers
Dear Margo: Restaurateur Dean Pashilis’ Tribute to Family, Food and Hospitality
Categories
- Art
- Articles
- Business of Luxury
- Celebrities
- Culture
- Entertainment
- Events
- Faces of Summer 2026
- Fashion
- Fashion & Style
- Featured
- Finance
- Food, Spirits, Wine
- Hamptons
- Hamptons Celebrities
- Health
- Health & Beauty
- Lifestyle
- Luxury Lifestyle
- Press
- Profiles
- Real Estate
- Technology
- The Chronicles
- Travel
- Uncategorized
- Weddings