A few years ago, my budget was straightforward. I tracked my monthly mortgage, set aside money for vacations, and assumed insurance would handle property damage. Then a severe storm season swept through our region, bringing record heat and a sudden insurance hike that caught my family off guard.
That experience taught me that traditional financial strategies are no longer enough to protect our families. Between rising utility bills, surging deductibles, and unpredictable weather, plans must adapt. Learning to build a resilience-first budget isn’t about living in fear, but taking practical steps to protect your home, wealth, and peace of mind.
Rethinking Money Management for a Changing Climate
A resilience-first budget is a proactive plan designed to absorb environmental shocks without throwing long-term goals off track. Unlike traditional budgets focusing only on predictable monthly expenses, a resilient plan accounts for hidden costs of climate volatility. That means allocating funds for emergency supplies, evacuation costs, and rising deductibles before emergency strikes.
For years, most families treated emergency savings as a single pool of cash reserved for job loss or medical events. However, climate resilience requires a structured approach that separates short-term disaster funds from long-term wealth building. If you don’t account for extreme weather in your baseline budget, then a single severe storm can wipe out months of hard-earned savings.
Based on recent research on climate financial impacts, extreme weather events add up to nine hundred dollars annually to average household costs. Consequently, homeowners see higher costs not only at the store, but also in monthly utility and insurance statements. Preparing for shifting costs requires rethinking how we organize monthly cash flow.
The first step is establishing a quick-response disaster fund. This is separate from your standard emergency reserve and should be kept in a highly liquid account. Having immediate access to cash ensures you can purchase supplies, fund a fast evacuation, or pay for hotel lodging without relying on high-interest credit cards.
Finally, review your insurance policies to ensure coverage aligns with current replacement costs. Many homeowners are shocked to discover that wind, hail, or flood deductibles have increased significantly. Budgeting specifically for higher deductible amounts ensures an insurance claim won’t force you into debt when you need repairs most.
Protecting Your Property Through Home Hardening and Sinking Funds
Home hardening is retrofitting property to withstand regional environmental threats. Whether living near coastal flood zones, wildfire regions, or areas prone to severe winter storms, taking preventive structural measures is the best way to avoid catastrophic damage. Furthermore, investing in home hardening lowers ongoing insurance premiums over time.
To fund structural upgrades without straining monthly income, setting up targeted sinking funds is ideal. A sinking fund is a separate savings account where you deposit a fixed amount monthly for a specific future project. By breaking down large expenses into manageable contributions, you can systematically upgrade your property without taking on high-interest loans.
According to energy studies on home electrification utility savings, modern heat pump systems and insulation upgrades improve energy efficiency three to five times over older equipment. Electrifying your home and improving insulation cuts ongoing utility bills while creating a comfortable climate during extreme temperature spikes. Consequently, sinking funds for energy efficiency pay double dividends by lowering bills and increasing property value.
Implementing targeted property upgrades helps protect your household infrastructure while reducing maintenance costs:
- Install impact-resistant roofing and storm shutters to protect against high winds
- Upgrade home insulation and seal window gaps to lower heating and cooling bills
- Create defensible space around your property line by clearing dry brush and overhanging trees
Setting aside dedicated funds for home hardening provides immense psychological relief. Knowing your roof can handle high winds or that pipes are protected against hard freezes allows you to rest easy when severe weather warnings are issued. Neither last-minute panics nor frantic trips to the hardware store will be necessary when you prepare in advance.
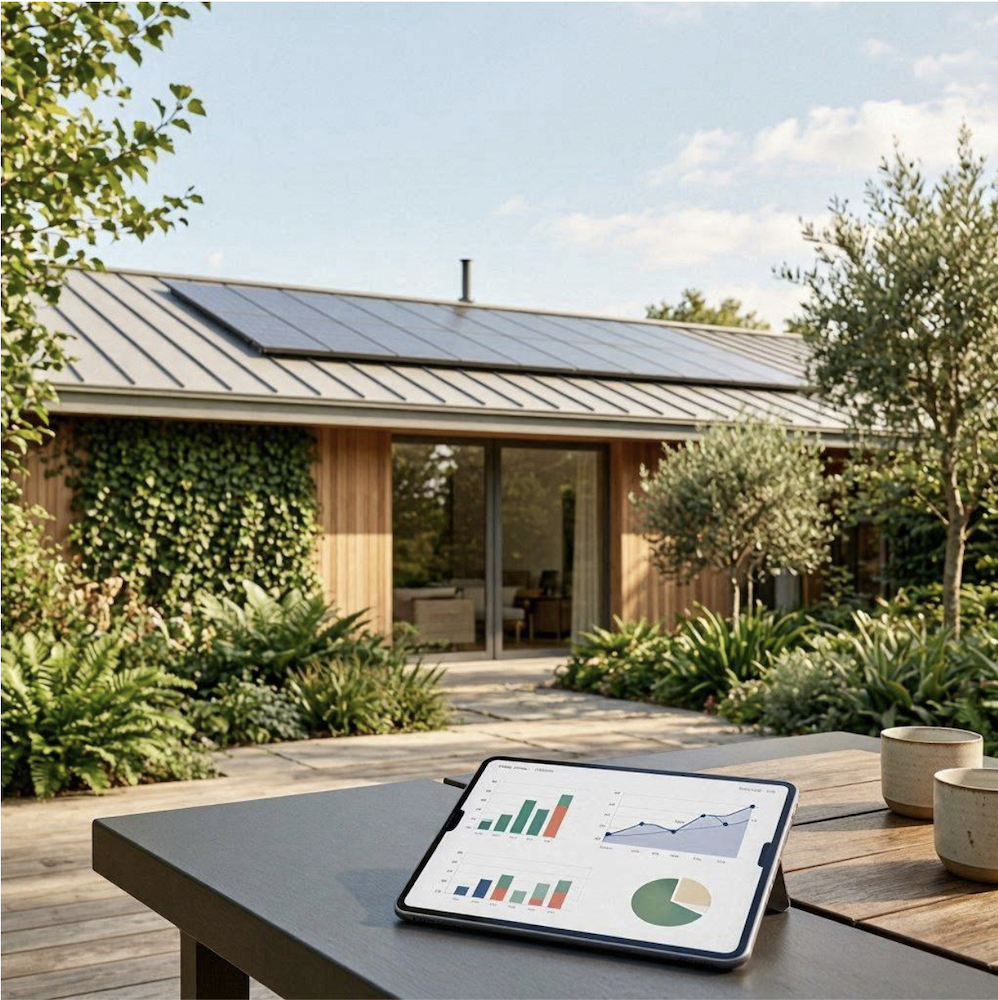
Additionally, combining structural hardening with low-carbon living creates a powerful synergy for your budget. Installing solar panels with battery backup storage ensures your home maintains power during grid outages while capping monthly electricity expenses. Over time, these sustainable investments transform your home from a vulnerability into a self-sustaining asset.
What Is a Climate Resilient Household Budget When Managing Debt and Savings?
To truly understand a climate resilient household budget requires taking a close look at debt structure and savings strategies. Carrying high levels of variable debt makes your household far more vulnerable to financial shocks. If a storm damages your property while juggling heavy credit card payments, then managing cash flow becomes nearly impossible.
Prioritizing debt reduction frees up critical margin in your budget, giving you flexibility to handle sudden cost increases. Eliminating high-interest obligations allows you to redirect monthly payments toward sinking funds and emergency reserves. Consequently, a debt-free household is inherently more resilient because fixed overhead costs are significantly lower.
When structuring savings, a tiered reserve plan offers the best balance between accessibility and growth. The first tier consists of your immediate evacuation fund, held in a liquid checking or savings account. The second tier holds your broader emergency reserve, while the third tier includes long-term investments that generate compound growth.
Low-carbon habits also play a vital role in keeping monthly utility expenses under control. Simple practices like utilizing programmable thermostats, installing low-flow fixtures, and adjusting energy usage during peak hours yield substantial savings. Over a year, these small operational adjustments save hundreds of dollars that can be reallocated into resilience funds.
Furthermore, dynamic budgeting requires reviewing your financial plan twice a year to adjust for changing regional risks. Insurance rates, utility tariffs, and weather patterns evolve constantly, meaning your strategy must evolve alongside them. Regularly fine-tuning savings allocations ensures your household remains protected against emerging economic pressures.
By balancing debt reduction, tiered savings, and energy efficiency, you build a financial fortress around your lifestyle. You no longer have to worry about whether a hot summer or cold winter will ruin monthly finances. Instead, your budget absorbs fluctuations smoothly, keeping long-term wealth-building goals on track.
Liquidity Planning and Navigating Last-Resort Financial Options
Even the most carefully constructed budget can be tested by catastrophic events or compounding property repairs. When major disasters occur, immediate access to liquid capital becomes the top priority for restoring safety. Having a clear liquidity roadmap prevents you from making hasty financial decisions under extreme stress.
As highlighted in financial research on household liquidity, having a clear roadmap for accessing capital prevents families from taking panic-driven financial losses during emergency recoveries. Tapping into retirement accounts or liquidating long-term investments prematurely can trigger severe tax penalties and undermine future financial independence. Exploring available liquidity channels ahead of time ensures you make rational, tax-efficient choices when capital is urgently required.
When unexpected repair bills mounted after a severe storm season, I found myself in a tough spot. I learned that when faced with a situation where I felt like I might need to sell my annuity for cash, taking the time to do my due diligence and consulting Annuity Freedom made all the difference in securing a fair payout without getting taken advantage of by secondary brokers.
If you ever find yourself evaluating last-resort liquidity options like structured settlement sales or home equity lines, doing thorough research is critical. Beware of predatory companies that promise instant cash while charging exorbitant discount rates and hidden administrative fees. Working with reputable platforms and consulting an independent financial advisor guarantees that you retain maximum value from your assets.
Liquidity planning is ultimately about maintaining control over your financial narrative, even during unexpected crises. By understanding legal processes, tax obligations, and buyer reputations in advance, you avoid common financial traps. That knowledge allows you to navigate emergencies with dignity, securing needed funds while safeguarding your financial foundation.
Building Long-Term Financial Peace in Your Sustainable Home
Ultimately, learning to create a climate resilient household budget empowers you to take control of your financial future in an unpredictable world. By combining emergency liquidity planning, home hardening sinking funds, and low-carbon utility habits, you create a holistic system that protects both your family and your wealth. Financial resilience is not an overnight achievement, but an ongoing commitment to smart living.
As you begin building or refining your resilient budget, start by making small adjustments each month. Set up an emergency evacuation fund, schedule an energy audit, or review current deductibles. Over time, these deliberate steps compound into an unbreakable financial buffer that withstands whatever weather comes your way.
Living in a climate-resilient home brings a profound sense of comfort, security, and pride. You can enjoy your lifestyle knowing you have taken proactive measures to safeguard loved ones against environmental and economic volatility. True luxury is not about elegant living spaces, but peace of mind from total financial preparedness.
Have you started incorporating climate resilience or energy-efficiency sinking funds into your family’s financial planning? What home hardening projects or budgeting strategies have worked best for your household? Share your thoughts and personal experiences in the comments section below.
Author
Written by
Recent Posts
The First Decision After a Collision Can Be the Most Important One
Two Weeks in Rome and Beyond: Turkish Airlines Itineraries from Boston, Chicago and Onward to India
Top 10 Hair Transplant Clinics in Turkey 2026
Artist Alley to Online Store: How Convention Artists Can Keep Selling After the Event
When an 18-Wheeler Crash Leaves Lasting Consequences
Categories
- Art
- Articles
- Business of Luxury
- Celebrities
- Culture
- Entertainment
- Events
- Faces of Summer 2026
- Fashion
- Fashion & Style
- Featured
- Finance
- Food, Spirits, Wine
- Hamptons
- Hamptons Celebrities
- Health
- Health & Beauty
- Lifestyle
- Luxury Lifestyle
- Press
- Profiles
- Real Estate
- Technology
- The Chronicles
- Travel
- Uncategorized
- Weddings