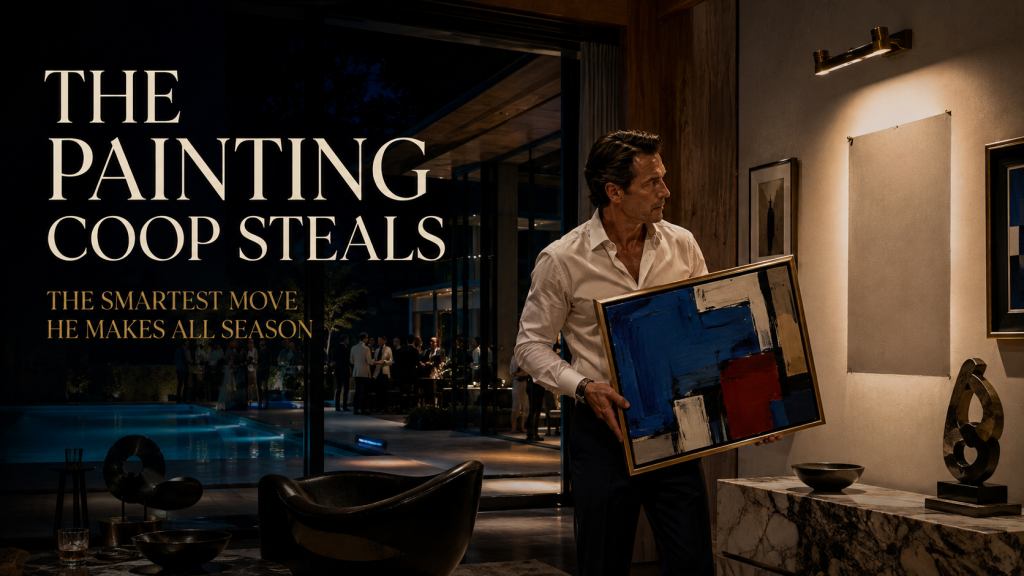
Treating art as an asset is the one financially literate thing anyone does in Your Friends and Neighbors, and it happens during a burglary.
Season one ends with Coop skipping a meeting where his old boss plans to offer him his job back. Instead he uses what he knows about Jack’s schedule, lets himself into the house, and takes a painting.
Every other theft in the series is a watch or a piece of jewelry. This one is different in kind, not degree, and the show never explains why. So we will.
Why a Painting and Not Another Watch
Watches are portable, liquid and stamped with a serial number. That last detail is the problem. Dealers check. Auction houses check. Insurers keep lists, and collectors online are relentless about spotting a stolen reference.
Art carries no serial number. It carries provenance instead, which is a paper trail rather than a stamp, and paper trails have gaps.
Famous works are unsellable, of course. Nobody moves a recognized masterpiece. But the enormous middle of the market behaves nothing like a Patek. Good pieces, respected names, thin registry footprints.
We priced the watch side of the same show in the $360,000 watch closet, including what a fence realistically pays for a serialized piece.
The Victim Who Cannot Complain
Here is the sharper reason the painting is the smart theft, and it has nothing to do with resale.
Coop steals from Jack. A man in Jack’s position weighs whether a police report is worth the questions that follow. Claims produce appraisals. Appraisals produce records. Records produce interest.
Not every wealthy household wants a full accounting of its walls entered into a file. The show never spells this out. Still, it is the most realistic thing in the sequence.
Stealing from someone who cannot make noise is not burglary. That is closer to a negotiation.
Art Does Not Behave Like the Rest of the Drawer
For legitimate owners, and most readers here are legitimate owners, art behaves unlike anything else on the personal balance sheet.
There is no daily price. No bid, no ask, no screen to check on a bad Tuesday. A piece is worth what the next buyer decides, and the next buyer may be eighteen months away.
So art is useful for some purposes and terrible for others. Useful for holding value across generations without a public mark. Terrible for anyone needing cash this quarter.
Coop’s whole crisis is a liquidity crisis. So he steals the one asset class that solves nothing about liquidity. That makes him an idiot, or it makes the theft about something other than money.
The Appraisal Everyone Skips
Ask an East End owner when their collection was last appraised and watch the pause.
Values move in both directions. A piece bought at a benefit auction in 2014 may be worth a multiple today. It may also be worth far less. The number in the insurance file is neither.
Appraisals should be refreshed on a schedule, not after an event. Every three to five years is common professional guidance. Living artists with moving markets need it more often.
Photograph everything. Keep invoices, condition reports and the provenance file somewhere other than the house that holds the art. Anyone who has filed a claim knows documentation is the entire game.
Where Art Claims Actually Fail
Standard homeowner policies treat fine art the way they treat watches, which is to say badly.
Schedule the pieces. A fine art rider covers named works at agreed value. So there is no argument about depreciation, and none about what the work was worth the day it vanished.
Transit is where claims most often go wrong. Art moves for restoration, for loan, for a shoot, for a change of house. Coverage frequently thins the moment a piece leaves the wall. Confirm transit before anyone touches the frame.
Also ask about vacancy language. A house empty from October to May sits in a different risk category than one in use, and some carriers price it that way. That exposure is covered in nine months empty.
Storage, Transit and the Winter Problem
The East End is a difficult environment for art, and almost nobody plans for it.
Salt air and humidity swings do real damage. So does a house left unconditioned for months. Works on paper suffer first, then anything with an organic support, then anything already restored.
Serious collectors out here run one of two systems. Either the house stays climate controlled all winter at real cost, or the good pieces leave in October for professional storage and come back in May.
Of the two, the second is cheaper and safer. It also removes the most attractive category of object from an empty house. Nobody puts that benefit in the brochure.
The Honest Case Against Art as an Investment
Every article like this owes the reader the other side, so here it is.
Transaction costs are brutal. A buyer’s premium in the twenties at the major houses. A seller’s commission on the way out. Then insurance, storage, framing, restoration and transport across the holding period. A piece must appreciate substantially before you break even.
The market is thinner than the headlines suggest. Records get set at the top by a handful of names. Meanwhile the vast middle trades slowly, or not at all.
So the only reliable rule is the oldest one. Buy the piece you want to live with. Treat appreciation as a surprise rather than a plan. Then insure it as though the appreciation is real anyway.
The Benefit Auction Problem
Out here there is a specific way art enters a house, and it happens in a tent in July after two glasses of something cold.
Benefit auctions are wonderful for the charity and complicated for the buyer. Paddles go up for social reasons. Prices reflect the room rather than the market. The piece arrives home with no provenance file and no appraisal.
Three summers later nobody remembers what was paid. Nobody remembers whether it was insured, or who the artist was. That is how a wall fills with objects of unknown value.
None of which is an argument against bidding. Bid. Just get a receipt, a condition note and the artist’s full name before the tent comes down.
What Ashe’s Walls Were Worth
The show’s most extravagant art moment is not a theft at all. It is set dressing.
Production designer Anu Schwartz dressed Owen Ashe’s house with museum-quality reproductions. Implied values run from $30 million and $40 million up past $100 million. Reproductions, obviously. But the implication is the character note.
Ashe does not appear to like any of it. He buys certainty, and a wall of blue-chip names is the most certain thing money can hang.
Contrast that with Jack. He owns one painting worth stealing and no need to explain it to anyone. The gap between those two collections is the gap between the two men. That reading continues in the Westmont Village files.
How Family Offices Actually Hold It
At a certain level, art stops being decoration and starts being a line item.
Pieces get held in an entity rather than personally, which is standard practice in how generational wealth is structured. That structure simplifies estate planning, clarifies ownership across a family, and keeps a collection from being split badly in a bad year.
Art lending is the other tool. Specialist lenders advance against a collection, so the owner keeps the work on the wall and frees capital anyway. Rates are not cheap. Still, it beats selling into a slow market.
Because that is the recurring lesson here. The families who do best with art are the ones who never have to sell on someone else’s timeline.
Anyone running a family office already knows this. Anyone whose wealth arrived in the last five years usually does not, and learns it during the first bad quarter.
Four Questions Before You Buy
Ask these before the paddle goes up, not after.
- Would I want this if it never appreciated? If the answer is no, walk. That single filter kills most bad purchases.
- Who else sells this artist, and at what? A price with no comparables is not a price. It is a hope.
- What does it cost to own annually? Insurance, storage, conditioning and eventual conservation. Budget it before you buy, not after.
- Where does it live in February? If the answer is an empty, unheated house on the ocean, you have a problem you have not priced.
None of that is complicated. Yet almost nobody runs the checklist, because buying art is an emotional act dressed as a financial one.
The East End Bought Early and Never Noticed
One local footnote worth remembering. This place was an art colony long before it was a status address.
The Abstract Expressionists came out to Springs and East Hampton in the years after the war, mostly because it was cheap. Jackson Pollock and Lee Krasner bought a farmhouse on Fireplace Road. Willem de Kooning built a studio nearby. They were not making an investment. They were leaving the city.
Their neighbors bought work directly, sometimes in trade, often for very little. Those pieces are now the most valuable objects in several unremarkable houses out here.
So the East End already ran the experiment. Buy what you love, from people you know, before anyone else agrees. Then wait forty years and try not to sell.
Where The Conversation Continues
Social Life Magazine reaches the walls described above. Owners, collectors, and the advisors who quietly tell them what to do next.
The summer issue lands in 25,000 East End homes. The list runs 82,000 deep. On July 24 and July 31, 2027, it converges on a lawn in Bridgehampton for Polo Hamptons. That tent holds more unappraised art than any auction house in the county.
Galleries, advisors, appraisers, storage firms and specialty insurers each get one seat here. Reach the editorial desk before the 2027 season is placed, because the summer issue closes months ahead of the lawn.
Author
Written by
Recent Posts
Best House Cleaning Services in Alpharetta, GA
The Ultimate Guide to Moving into New York’s Most Exclusive Neighborhoods
Medical Malpractice Cases Chicago: Understanding Your Legal Rights
Legal Rights and Remedies Following Sexual Assault by a Police Officer
Choosing the Best Drunk Driving Victim Lawyer for Justice for the Injured
Categories
- Art
- Articles
- Business of Luxury
- Celebrities
- Culture
- Entertainment
- Events
- Faces of Summer 2026
- Fashion
- Fashion & Style
- Featured
- Finance
- Food, Spirits, Wine
- Hamptons
- Hamptons Celebrities
- Health
- Health & Beauty
- Lifestyle
- Luxury Lifestyle
- Press
- Profiles
- Real Estate
- Technology
- The Chronicles
- Travel
- Uncategorized
- Weddings